Grow more.
Earn more.
Worry less.
A Landbank loan at 3% a year, inside the planting window — then a per-plot AI planting protocol that a farmer follows to lift his own yield, crop insurance, and a buyer already contracted.
Farmers who follow the protocol earn about ₱180,000 more a year — nine times what the platform costs them.
The four engines
One platform, four ways to lift income
Every engine is a concrete, measurable lift to the bottom line of the farm.
Capital at 3% a year
Landbank holds a ₱12 billion facility for smallholders at 3% a year. Frez.ai gets a farmer into it — instead of the trader at 72–99% or the “5-6” lender at 170–340%.
How the loan is priced →AI training, per plot
The average rice farmer gets 4.14 tonnes a hectare; on the same land, with the same seed, 5.7 to 7.5 is achievable. The gap is not weather — it is protocol, and protocol is what software is good at.
See the crop protocol →Cover for weather & pest
Crop insurance is written into the loan, so a typhoon or an infestation does not turn one bad season into years of debt. The season is protected before it is planted.
See what is covered →Matched to a real buyer
A buyer is contracted before planting and remits to the bank at harvest. The farmer sells at an agreed price, not at whatever the trader who financed him decides to pay.
See the buyer network →Why the farmer signs
Cheap credit is not why he signs.
Doubling his harvest is.
The income comes from following the Frez.ai planting protocol — a per-plot calendar for variety, spacing, fertiliser rate and timing, water and pest thresholds, checked by satellite every fortnight. Same land, same seed, a different season.
Extra income a year, to the farmer
+₱180,000
₱150,000 of it comes from a bigger harvest grown by following the protocol, and ₱30,000 from borrowing at 3% instead of the trader's 24–33% a cropping season.
₱19,000
is what he pays Frez.ai — 5% of the loan in fees, plus margin inside inputs he was buying anyway.
9×
what he gets back for what it costs him. That ratio is why he enrols, follows the protocol and repays.
The yield gap, in tonnes a hectare
Achievable on-farm yields of 5.7–7.5 t/ha measured on smallholder plots, not research stations (Sebastian, Alviola & Francisco, FAO). The income above is underwritten at 6.5 t/ha — inside that band, not at the top of it.
The cost of a year's production credit
The same peso, three very different prices
Drawn to scale, 0 to 340% a year. The money is already there at 2 to 3%. Most farmers never reach it — 63.6% borrow informally, and only 1.4% borrow from a bank.
How it works
Five steps, one season
Rice goes in the ground in October. Today the file takes thirty-one documents from eight counters, then one to two months to release. Frez.ai closes that gap.
Apply
The farmer answers questions in his own language, on the app. It captures his government IDs and auto-fills the documents.
Review
Documents, credit investigation and plot survey assemble themselves. An officer confirms rather than compiles.
Approve
A thin-file score the bank's own credit committee will sign.
Release
Money leaves as inputs, not cash — geo-tagged and farmer-signed at the plot.
Collect
The contracted buyer remits to the bank. Repayment is swept at source, not chased.
Inside the app
From loan to protocol to buyer
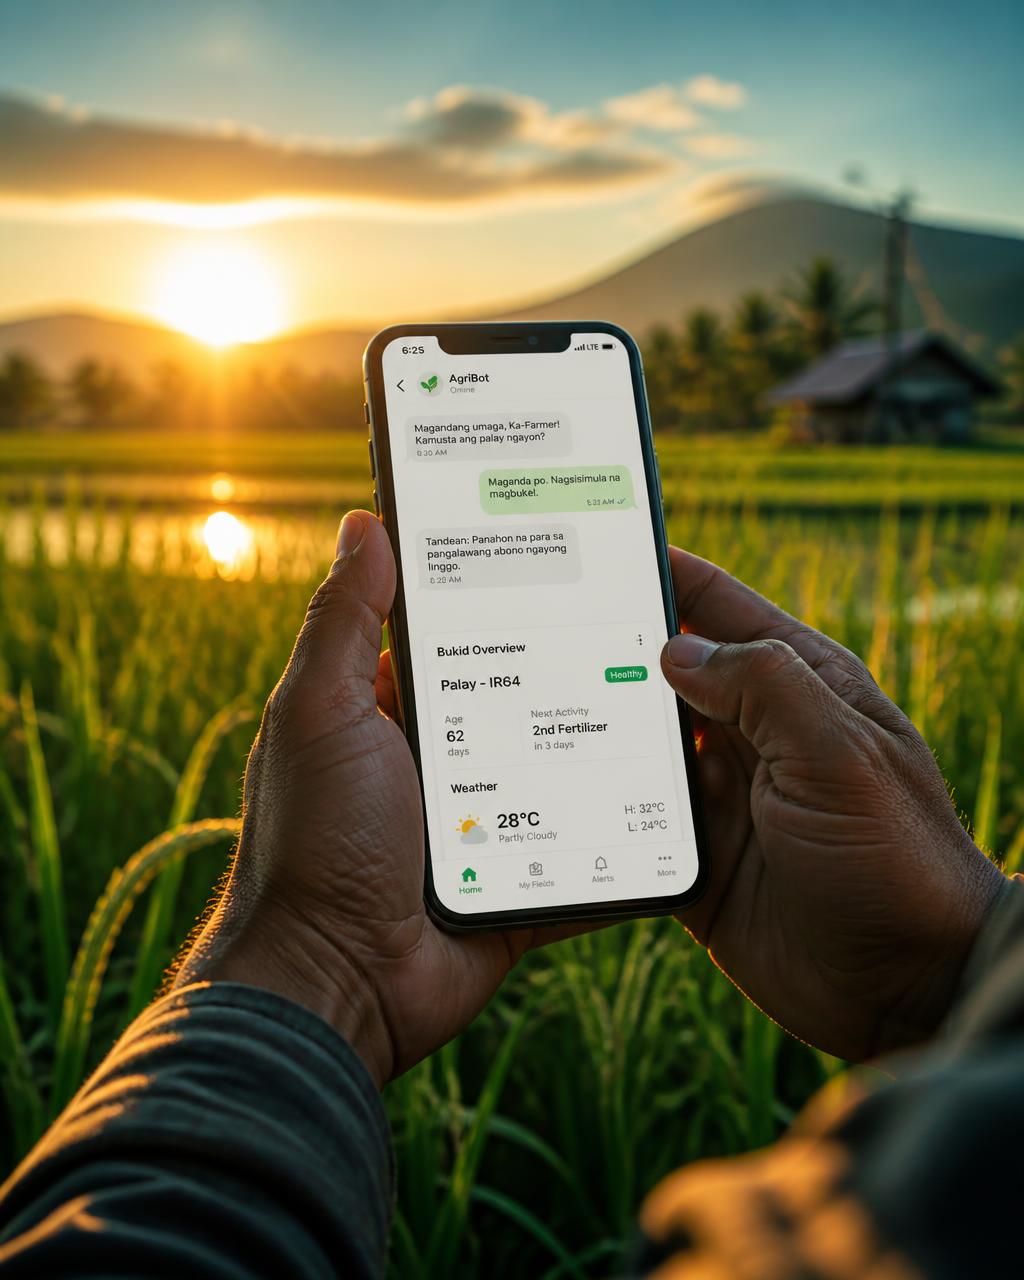
Six screens, one season: apply in Filipino, let the paperwork assemble itself, follow the protocol, and sell to a buyer who is already contracted.
01 · Apply
One conversation, in Filipino
Kuya AI asks what he plants and how much land he has. He answers by voice or tap — no forms, no queue. The app captures his government IDs as he goes.
Kuya AI
Nakikinig · Tagalog
Magandang umaga! Ano po ang itinatanim ninyo?
Palay po, 2 ektarya sa Bohol.
Salamat. Qualified po kayo sa Landbank Agrisenso Plus — 3% kada taon.
Ano ang kailangan kong papeles?
Wala po. Kami na ang bahala sa 31 dokumento. 🌾
Kuya AI · application
02 · Draft
Landbank's own form fills itself
Nineteen fields on the bank's actual application form are drafted from that one conversation, and e-signed wherever the form allows it.
Agrisenso Plus
19 fieldsFull name
Juan D. Ramos
✓Barangay / Municipality
Poblacion, Ubay
✓Crop
Palay (inbred)
✓Area planted
2.00 ha
✓Loan amount
₱ 120,000.00
✓TIN
drafting…
17 of 19 fields drafted from one chat
Landbank form · auto-filled
03 · Assemble
Seventeen documents from one record
The MAO certificate, barangay clearance, sketch map, TIN verification, PCIC enrolment and the rest are generated and routed for signature. 31 documents become 0 for the farmer; 8 counters become 1.
31
documents before
0
for the farmer
MAO certification
01Barangay clearance
02Plot sketch map
03TIN verification
04PCIC insurance enrolment
05Credit investigation sheet
0604 · Grow
The protocol, watched by satellite
Every plot gets its own calendar. NDVI is read each fortnight, and days 30, 60 and 75 are release gates — the next tranche of inputs only moves when the crop is confirmed. A sick leaf photographed comes back with a diagnosis and a paid-for remedy.
Plot 2A · protocol calendar
satellite verified
Day 0
Land prep · inputs released
Day 30
NDVI 0.62 · gate passed
Day 45
Pest flagged · remedy paid
Day 60
NDVI 0.78 · gate passed
Day 75
Final tranche released
Day 110
Harvest window
0.78
NDVI
3 / 5
Gates
96%
On protocol
05 · Plan
He sees the income before he plants
Move the slider and the model prices the season for his own parcel. Half rice, half ube projects ₱216,000 net — up 286% on all-rice — with the buyer already locked.
Projected net income
₱216,000
+286% vs all-rice · 2.00 ha
Crop mix
Palay · 1.0 ha
₱ 78,000
Ube · 1.0 ha
₱138,000
Income planner
06 · Sell & repay
A buyer contracted, repayment swept
The contracted offtaker remits to the bank at harvest at the agreed price. Saka Points, levels and a barangay leaderboard keep the protocol followed on the day it matters — the behaviour that predicts repayment.
Contracted buyer
Bohol Agro Traders
Agreed price
₱23.00 / kg
Trader price
₱17.50 / kg
Loan repaid
swept at source
₱120,000 of ₱120,000 · 0 days late
1,840 Saka Points
#3 in Barangay Poblacion
Harvest · repayment
The Frez loop
How income compounds
Four engines feed one flywheel. Cheap credit and AI raise the yield; insurance protects it; a contracted buyer monetises it at an agreed price — and the record of that season makes the next loan faster and cheaper.
31 → 0
Documents the farmer collects himself
For Landbank & investors
The bank keeps the balance sheet. Frez.ai runs the lending stack.
Enterprise software sold to a bank. The platform originates, underwrites, disburses and collects on the bank's own book, and is paid five recurring fees for the work — none of them interest. Frez lends nothing and holds no loan book — the bank keeps the asset, the spread and every peso of credit risk, and finally reaches a borrower it is mandated to serve.
₱12bn
Facility at 3% a year
31%
₱3.78bn lent to 15,200 borrowers
8 → 1
Counters the farmer visits
₱473bn
Production credit a year, 467 banks mandated
For buyers
Verified supply, on contract
Source traceable, quality-scored produce locked to forward contracts from farms that are financed, trained and insured through the season — so the volume you signed for actually arrives.
The window closes at planting
Talk to Frez.ai
Farmers, buyers, banks and investors all start the same way — a conversation. A live demo of the working platform runs on request.
hello@frez.ai